This is our third quarterly French Tech Funding Report, and it covers the strangest quarter of 2026 yet. You can access the full report in three ways. Below, we go through the headline numbers and what they look like once you take Mistral out. We also explain why the shrinking number of early-stage deals worries us more than any record set this summer.
Want to reach an audience of more than 30,000 readers each month? The French Tech Journal is the leading English-language media platform covering France's dynamic tech ecosystem. With 31,000 + engaged readers across key global markets and consistently high engagement rates, our sponsorships provide unparalleled access to decision-makers in French tech.
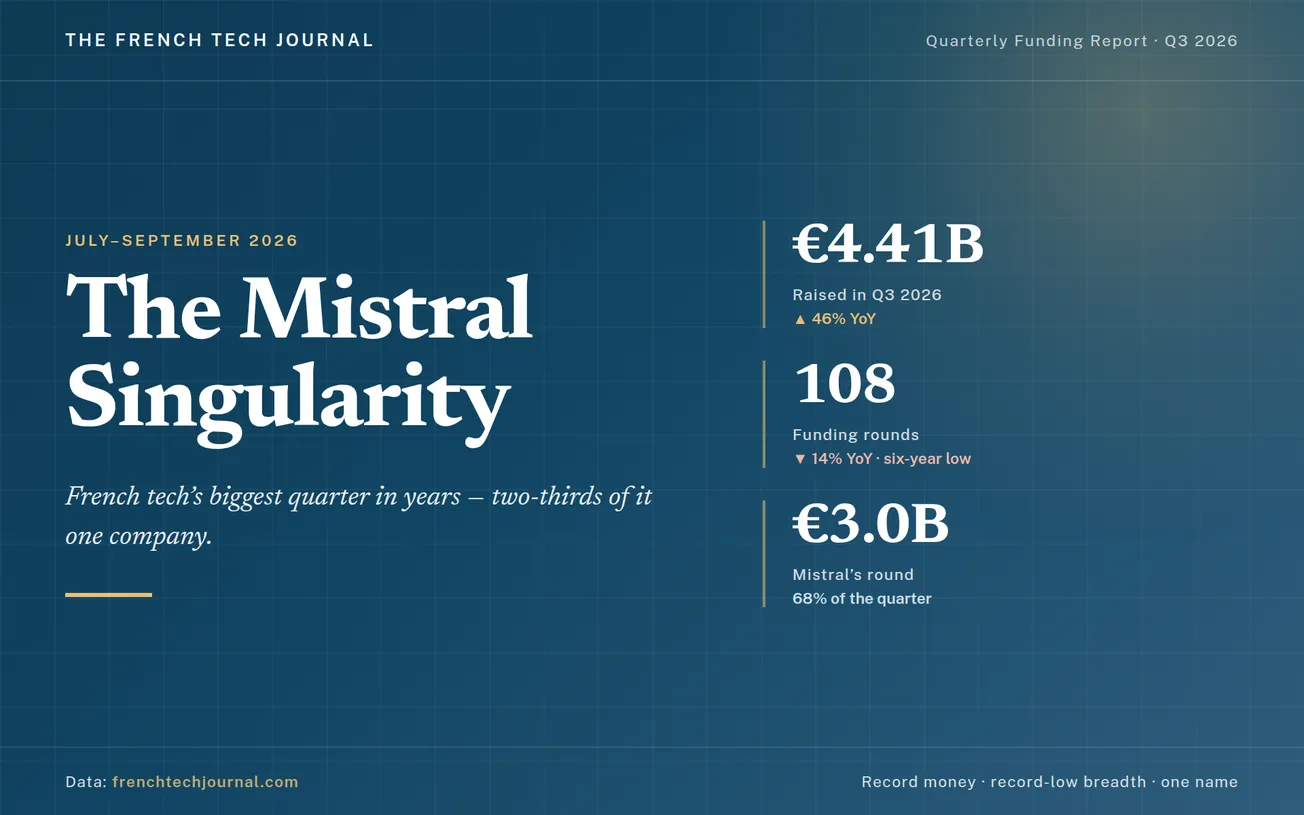
French tech just had its biggest summer on record. Between July and September, startups raised €4.41 billion, according to our French Tech Funding Tracker. That's up 46% from the same quarter last year and more than double the spring. It also beats every third quarter in the six years we've been counting, including the giddy days of 2021 (€3.96 billion).
Anyone reaching for the champagne should read the next paragraph first.
In September, Mistral AI raised €3 billion in a single Series D. It's the largest venture round in French history, and it accounts for 68% of everything French startups raised in the quarter. Take Mistral out and the total drops to €1.41 billion. That's still 18% more than last year's Mistral-free figure. But set aside each quarter's biggest deal and Q3 actually came in about 14% below Q2.
We called the first quarter of 2026 "The Great Concentration" and the second "Top-Heavy." We're calling this one The Mistral Singularity, because the trend we've been tracking all year has more or less hit its limit. When Alan's €480 million round made up 23% of Q2, that already looked lopsided. Mistral's share is three times bigger. Until now, Verkor held the record for a single deal, at 38.5% of Q3 2023.
A familiar name at the top
Mistral has done this before. The Paris lab also topped Q3 2025, raising €1.82 billion, or 60% of that quarter. So the year-on-year comparison really pits one Mistral round against another, and the company's slice keeps growing. Whether French tech has a good quarter now depends a lot on when one company decides to raise.
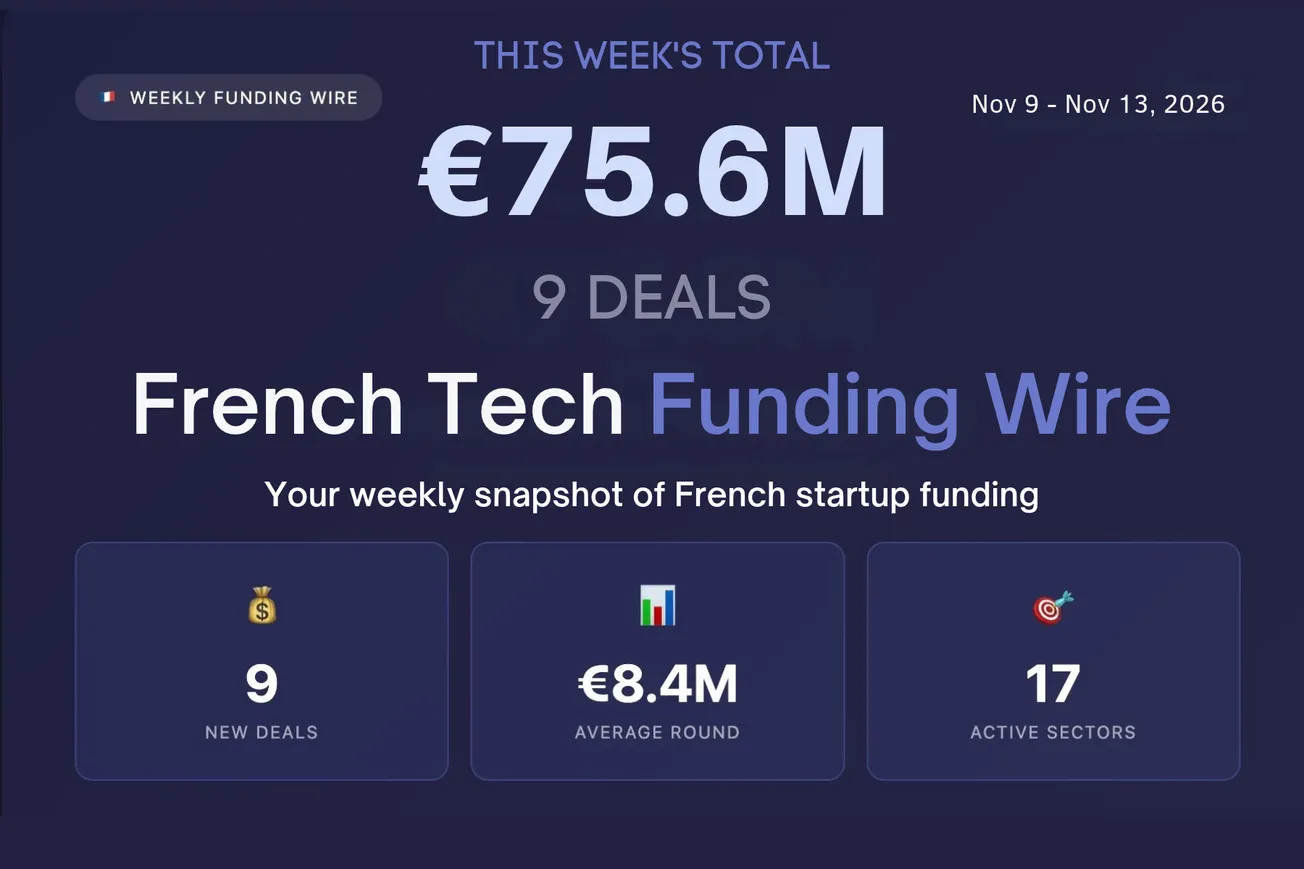
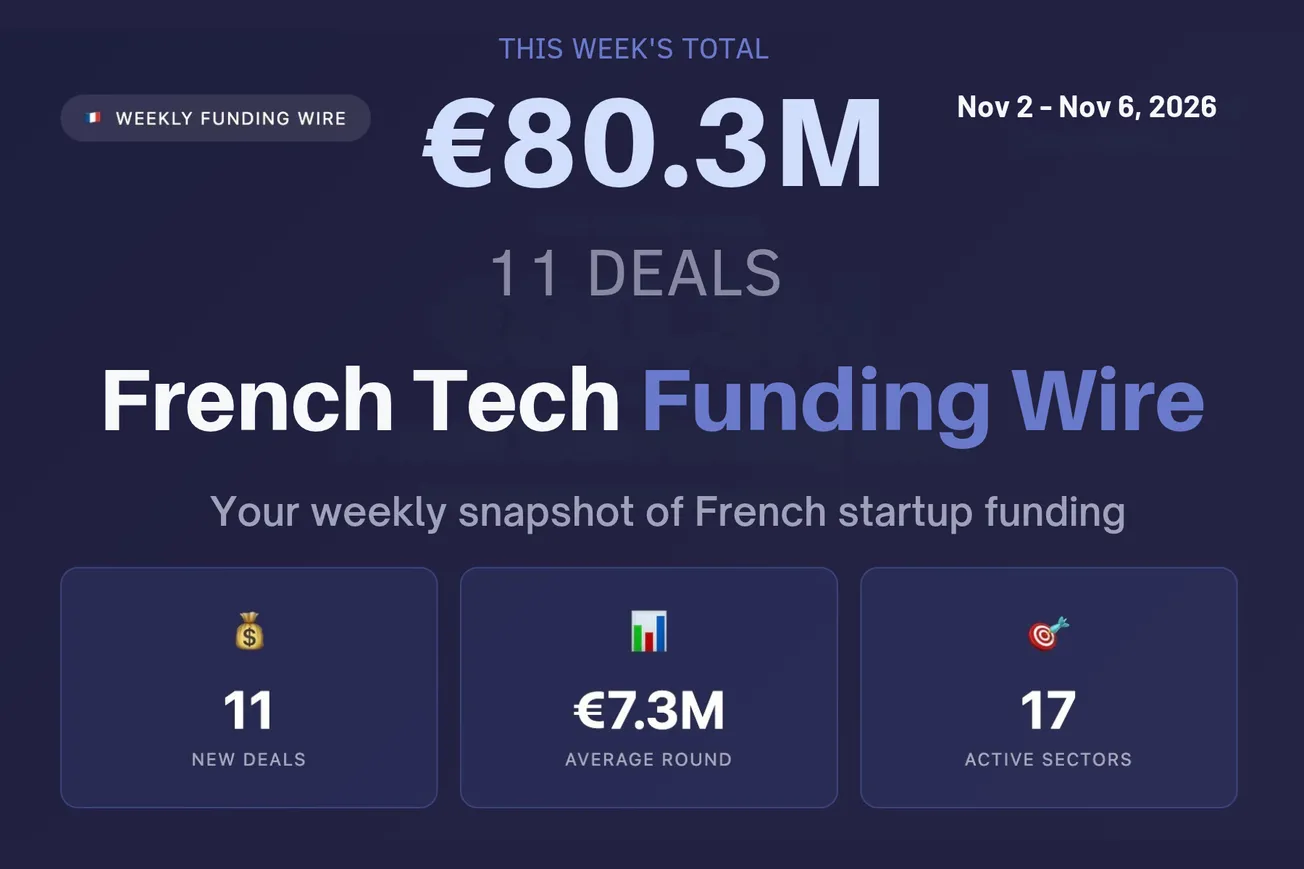
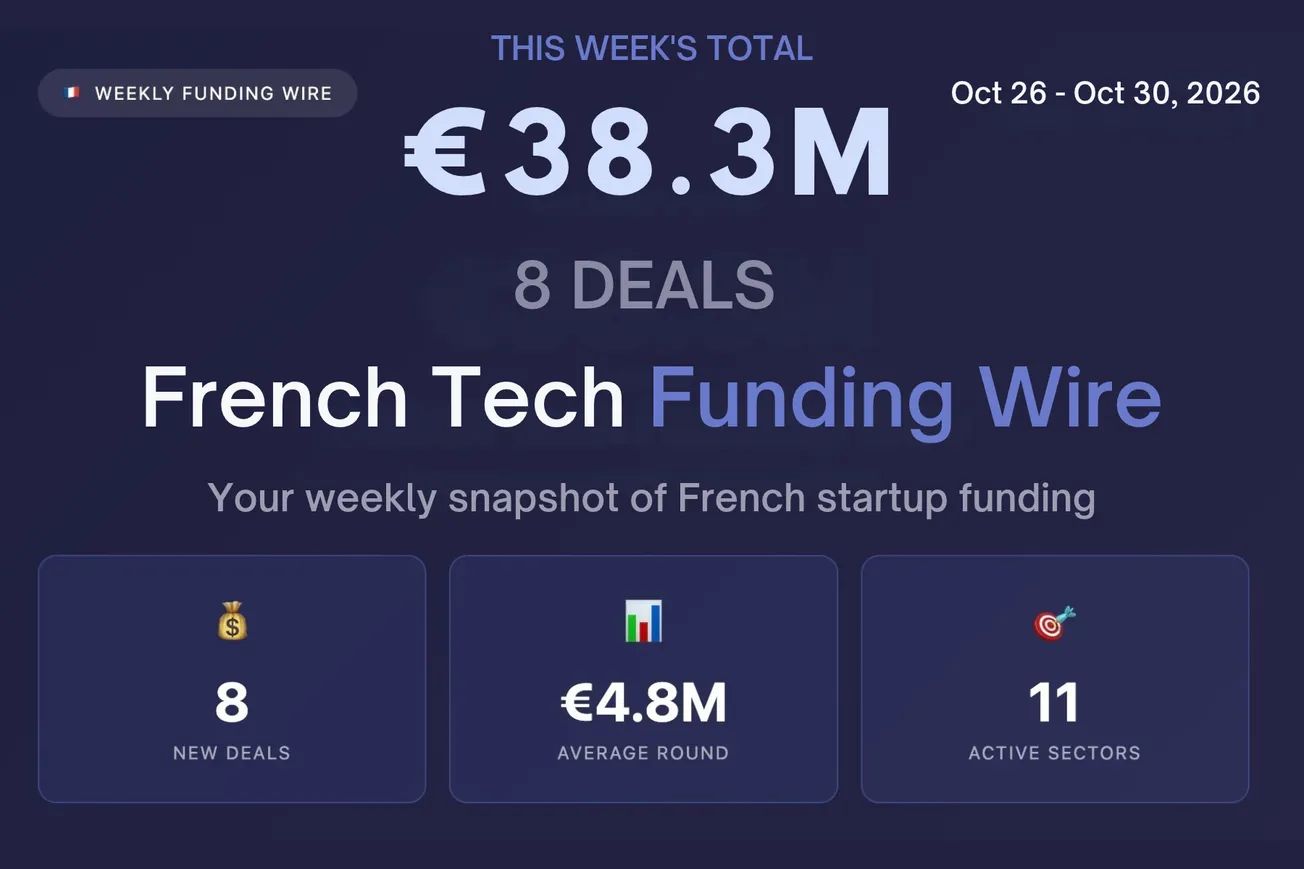
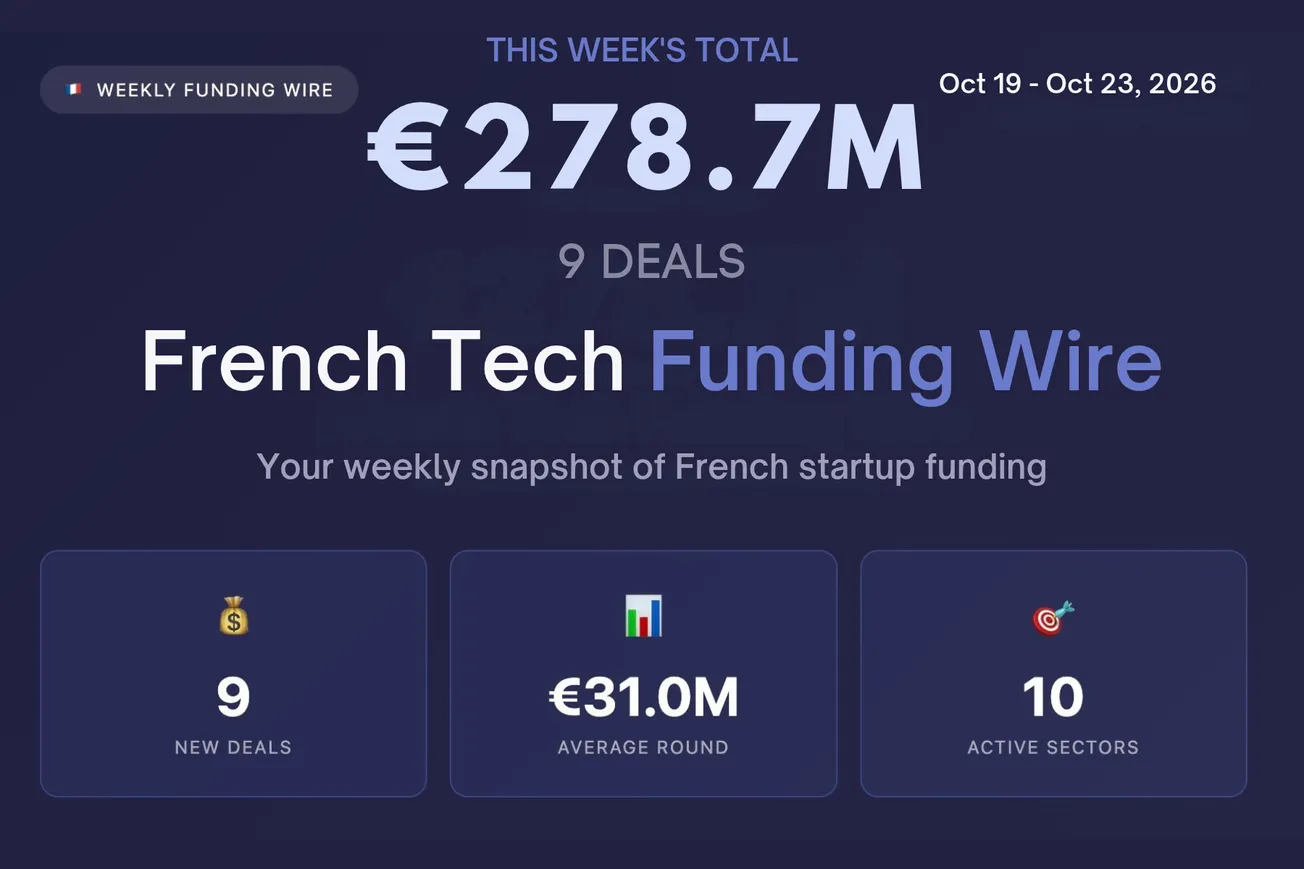
The calendar made the effect even starker. July was normal, with €485 million led by Skello's €150 million round. August was close to dead: €89 million across 14 deals, the deepest summer lull in our data. Then September brought in €3.83 billion, or 87% of the quarter, as Mistral, The Exploration Company (€387 million) and HighLife (€80 million) all closed within weeks of each other. Monthly funding went up 43-fold between August and September.
2026 has already beaten 2025
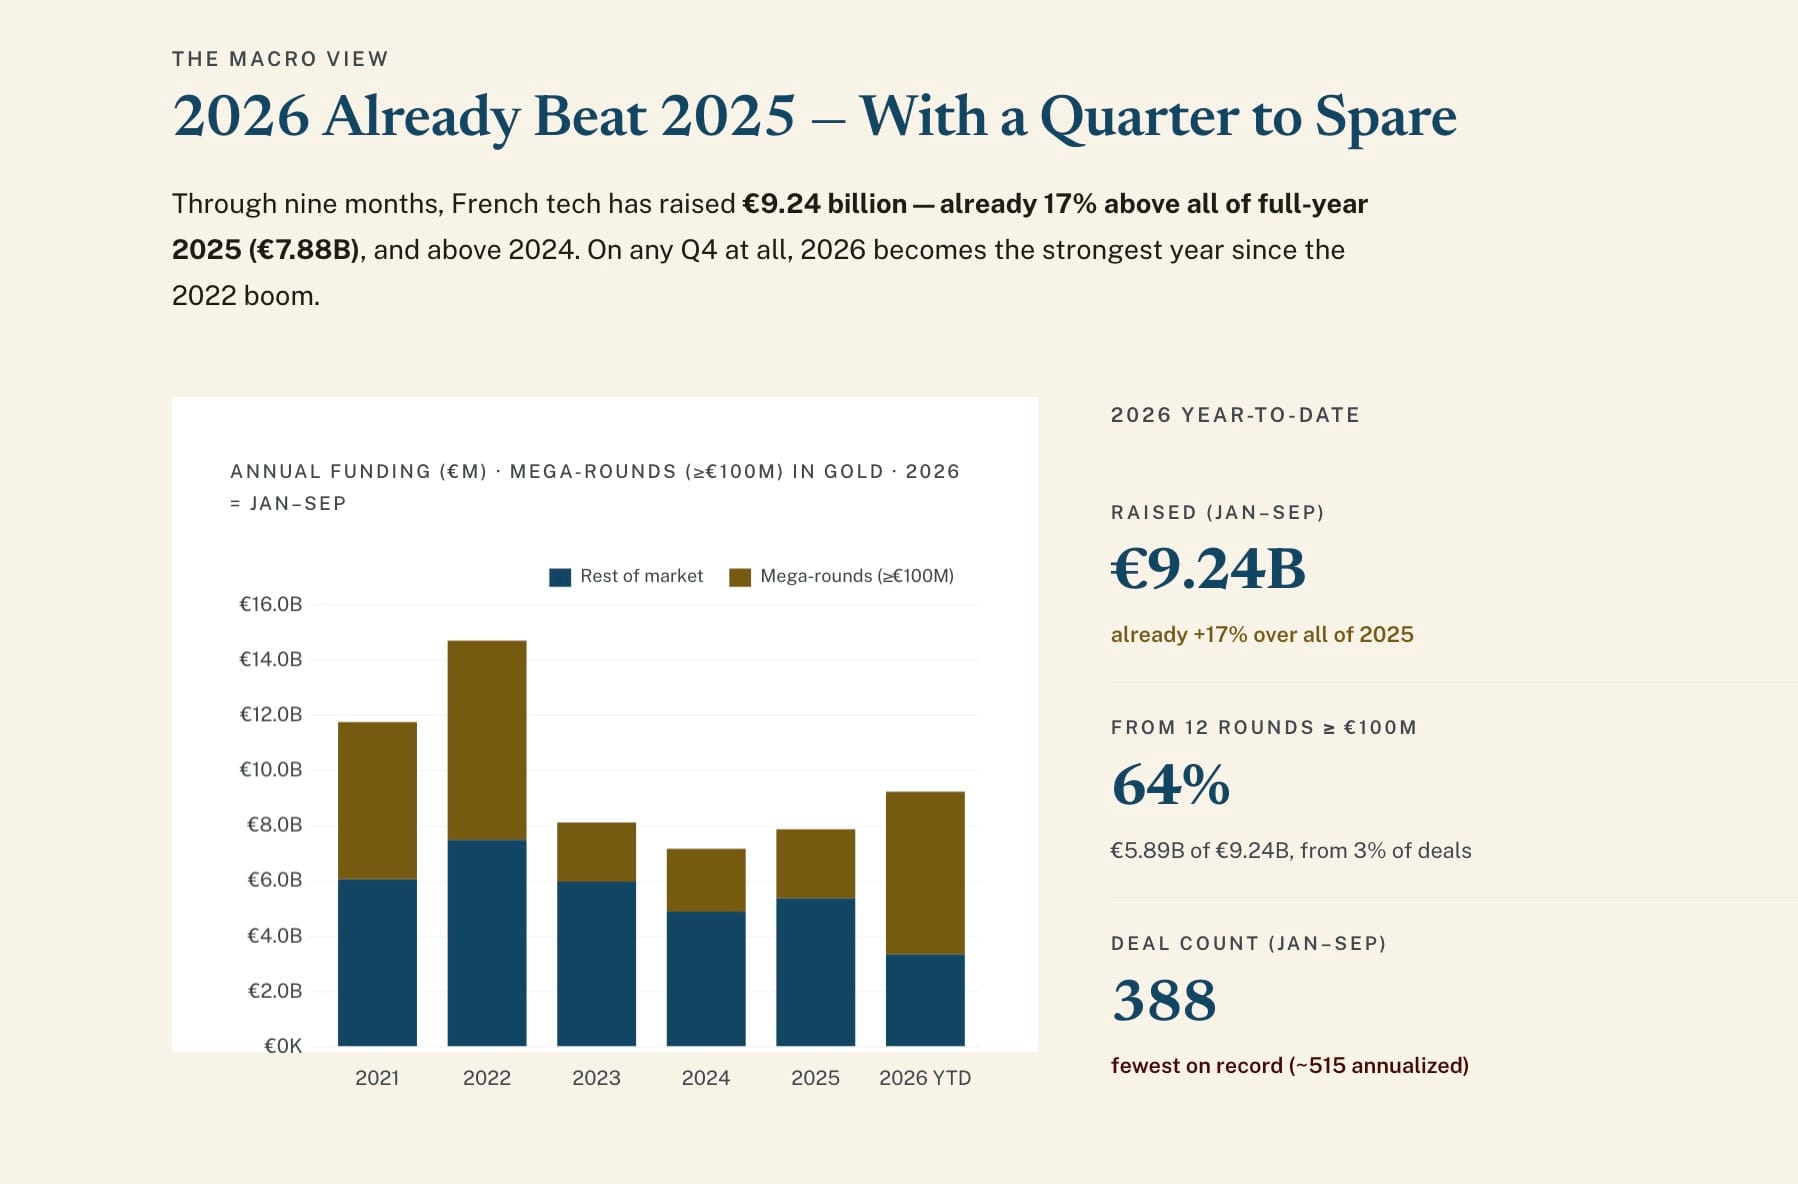
Pull back to the full year, and the picture looks even better. Through September, French startups have raised €9.24 billion. That's 17% more than all of 2025 (€7.88 billion) with a quarter still to go, which already makes 2026 the strongest year since the 2022 peak of €14.7 billion.
But look at who's doing the raising. The 12 rounds of €100 million or more account for €5.89 billion, or 64% of the year's money, and they're just 3% of the deals. The three biggest (Mistral, AMI at €890 million and Alan at €480 million) add up to 47% of the year by themselves. Mistral alone is roughly a third.
The deal count fills in the rest. There have been 388 rounds so far in 2026, which annualizes to about 515. That would be the lowest in our records, below 2025's 642 and well under half of 2022's 1,248. One odd wrinkle: the median round hit a six-year high in Q3, at €4.4 million. The typical deal is getting bigger. What's disappearing is the small end of the market.
AI, and then everything else
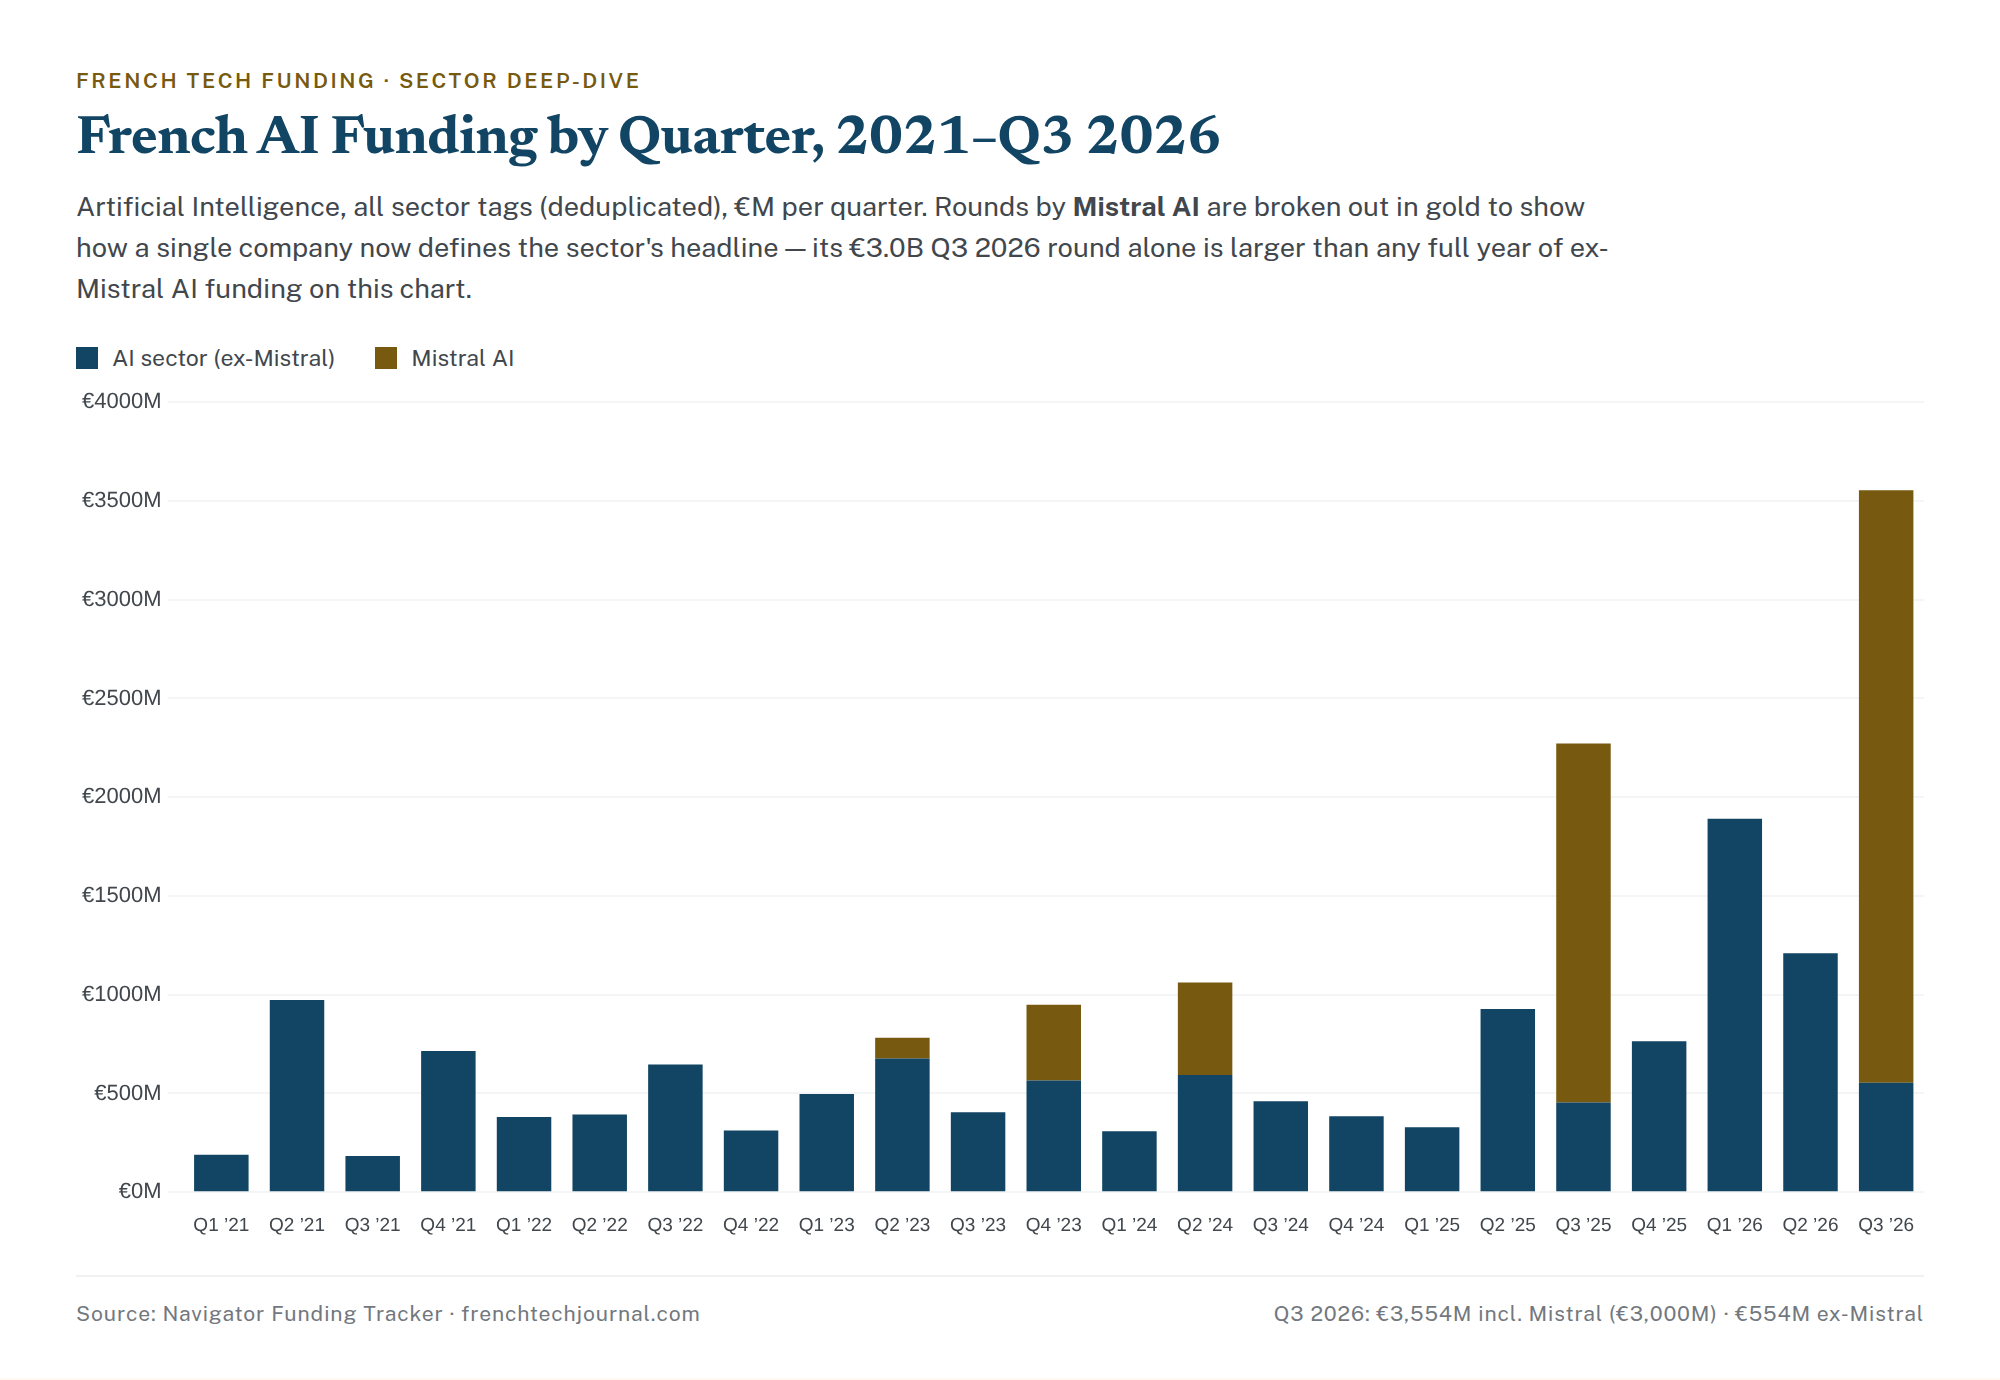
Mistral bends the sector numbers too. Counting each deal under every sector tag it carries, AI accounted for €3.55 billion this quarter, or 81% of the total. Subtracting Mistral and AI comes to about €554 million across 56 deals. That's still France's largest sector by a wide margin, and it's up roughly 22% on last year's Mistral-free figure.
Outside AI, space was the biggest mover. The Exploration Company, a Franco-German space firm based in Munich, raised a €387 million Series C, the quarter's second-largest round. That one deal pushed spacetech funding up more than sixfold on a year ago. Medtech and healthtech both bounced back by triple digits, though from low starting points. Energy, cleantech and hardware went the other way. Energy fell 86%, to just €33 million.
The base keeps shrinking
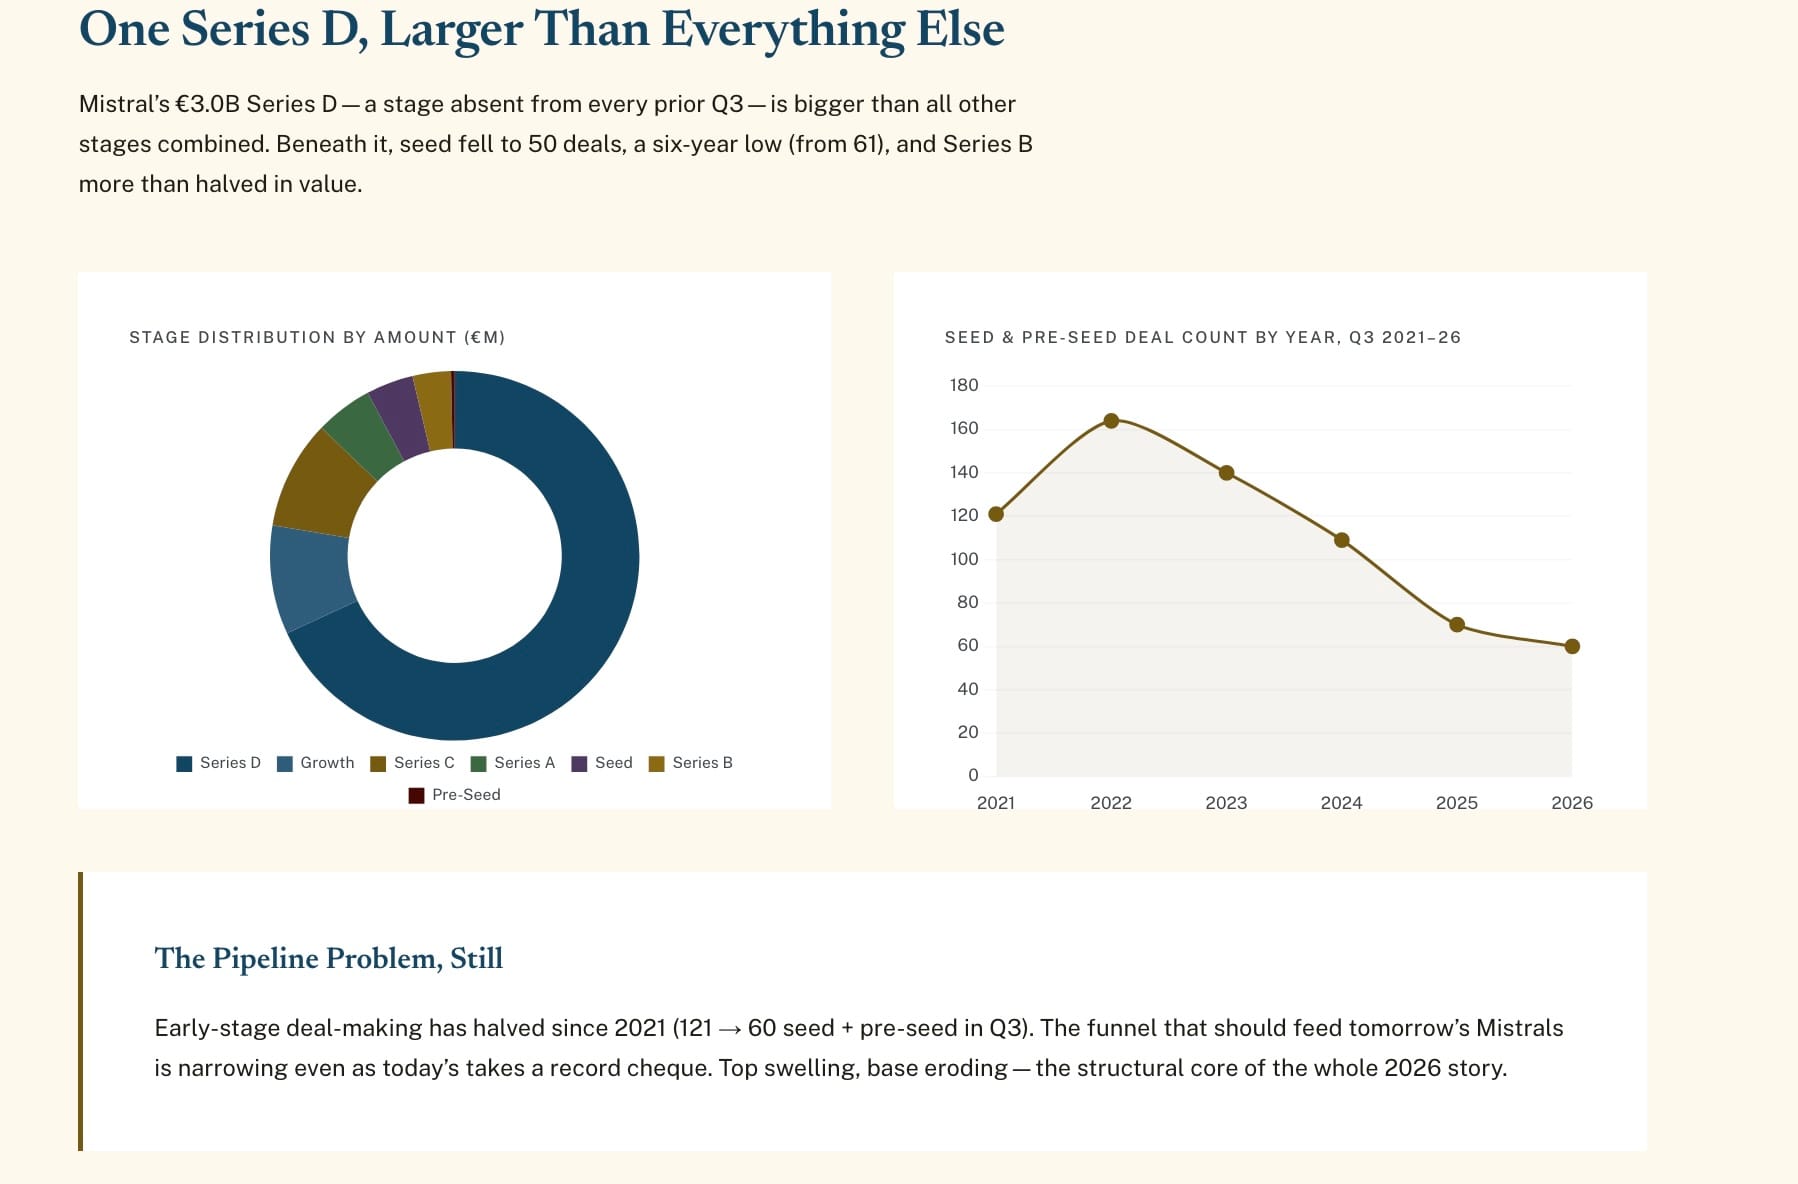
This is what worries us most, and it hasn't improved since spring. Seed deals fell to 50 this quarter, a six-year low, down from 61 a year ago and 104 in Q3 2022. Add pre-seed and the count has halved since 2021, from 121 deals to 60. Series A has dropped from 43 deals to 19 over the same stretch.
Meanwhile, Mistral's lone Series D, a stage that hadn't shown up in any previous third quarter, was bigger than every other stage put together. Those seed and Series A rounds are supposed to produce the next Mistral. Right now the top of the market keeps swelling while the pipeline underneath it narrows.
Bpifrance is doing much of the work holding that base up. The public investment bank took part in 27 of the quarter's 108 deals, one in four and its highest share this year. Business angels came next with 23. The busiest private fund, Kima Ventures, did six. As private capital crowds into a handful of huge rounds, the long tail of smaller deals leans more and more on the French state and on angels.
What to watch in Q4
Q4 should settle a few things. The first is the €10 billion mark. With €9.24 billion already in, French tech needs about €760 million more to clear it, which is less than any quarter this year has raised.
The second is whether Mistral is a one-off. A second French round above €1 billion, from a challenger or from Mistral itself, would suggest rounds this size are becoming normal.
The third, and probably the one that matters most, is the deal count. If it finally levels off, the thinning of the past few years was likely cyclical. If it keeps sliding, it's structural, which is a much harder problem.
Either way, 2026 is on track to be French tech's biggest year since the boom. Whether that counts as a triumph or a warning depends on whether anyone else can raise like Mistral. Otherwise, the ecosystem starts to look like one very large company and a very long tail.
👋🏻 If you’re enjoying The French Tech Journal, support the project by forwarding it to friends and sharing it on your social networks. You can also comment on this post. And if you have ideas for stories, tips, or just want to harass us, shoot us an email: chris@frenchtechjournal.com / helen@frenchtechjournal.com 👋🏻